The sales report looks excellent.
One decorative mirror has become the best-selling product in the collection. It sells faster than the other designs, attracts customer attention and appears to justify another large purchase order.
The buyer is ready to celebrate.
Then the finance team asks an uncomfortable question:
How much money does this bestseller actually make?
The answer may be surprisingly small.
A product can lead a home décor collection in unit sales while contributing less profit than a slower-selling item. Shipping, handling, product damage, returns, promotions and inventory investment can all change the economics.
For buyers looking for a practical home furnishings buying guide, the lesson is simple:
Sales volume tells you what customers buy. It does not tell you what your business earns.
The Bestseller Trap: Confusing Popularity With Profitability
Home décor buyers regularly make decisions using sales rankings.
The top-selling vase gets another purchase order. The most popular mirror receives additional stock. The fastest-moving decorative accessory becomes a priority for the next collection.
This approach is understandable. Sales performance is valuable evidence of customer demand.
But demand is only one part of the purchasing decision.
Consider two hypothetical products sold by the same retailer.
Product A is a decorative mirror with strong customer demand.
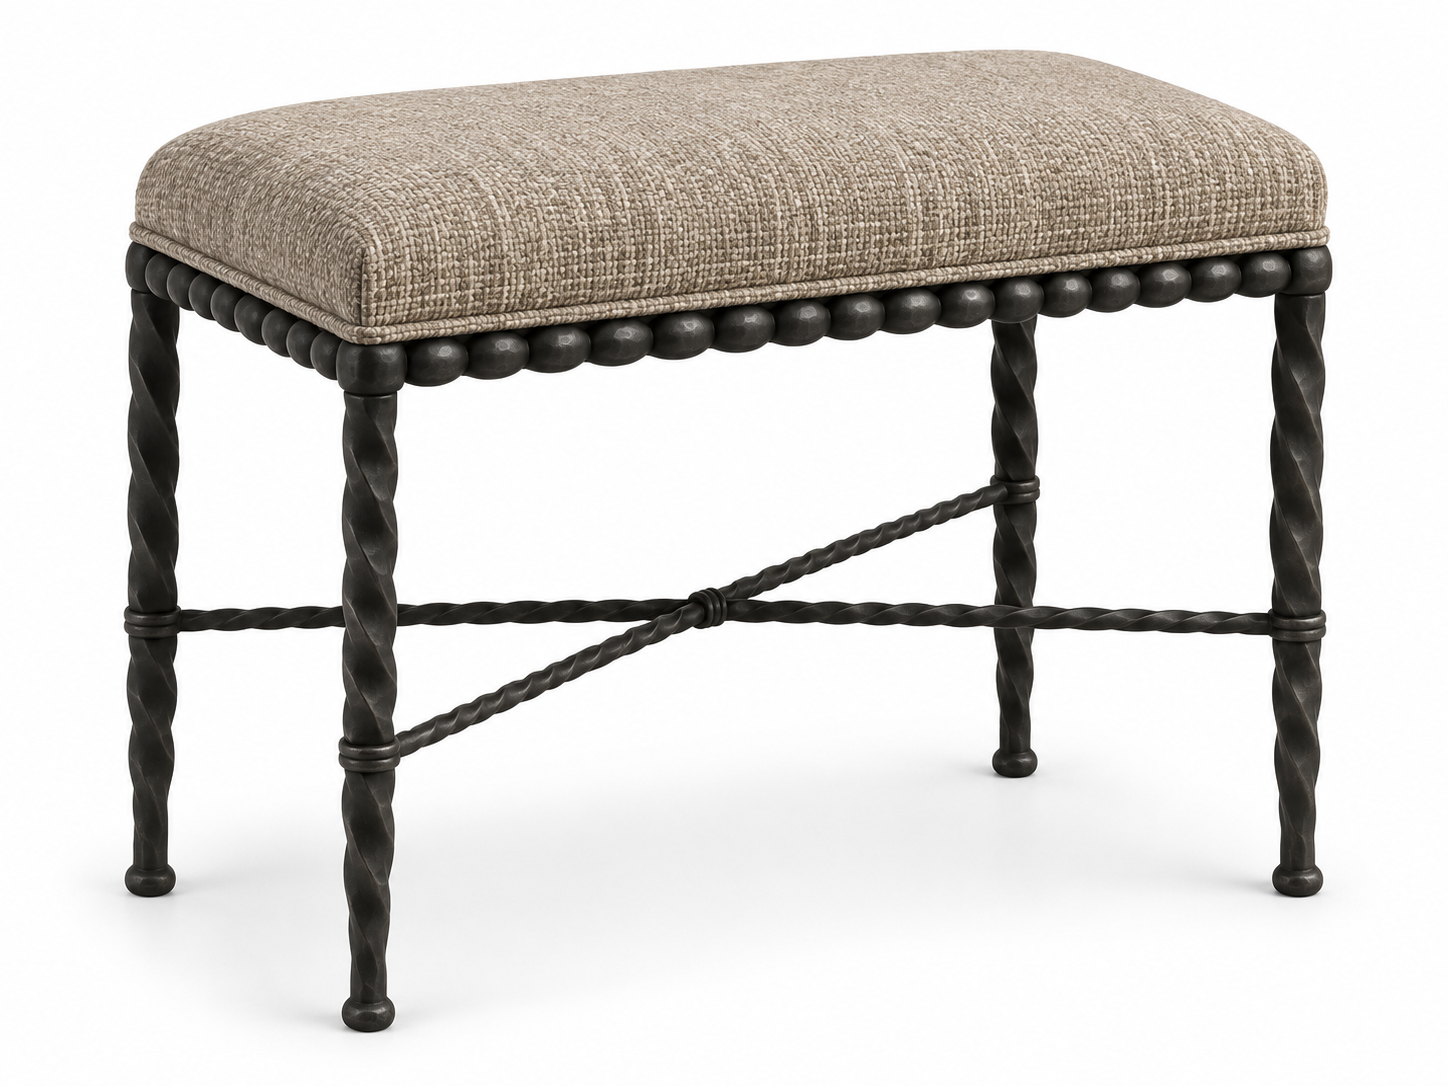
Product B is a compact upholstered accent stool that sells more slowly.
The mirror is the clear bestseller by unit sales.
Yet the commercial outcome looks different once the direct costs are considered.
Two Products. One Surprising Result.
The following figures are entirely illustrative, not Teruier sales data or actual product quotations.
| Monthly Performance | Product A: Mirror | Product B: Ottoman |
|---|---|---|
| Units sold | 120 | 70 |
| Selling price per unit | $79 | $99 |
| Landed product cost | $35 | $46 |
| Selling and fulfilment costs | $12 | $15 |
| Expected damage and return allowance | $12 | $5 |
| Attributable promotion cost | $10 | $10 |
| Contribution per unit | $10 | $23 |
| Monthly contribution | $1,200 | $1,610 |
The mirror sells 50 more units.
But the ottoman produces $410 more contribution during the same period.
This example uses a simplified contribution model; actual retailers must avoid double-counting refunds and allocate costs consistently.
The point is not that ottomans are more profitable than mirrors.
It is that a product’s sales ranking does not automatically reflect its contribution ranking.
The product that wins the sales chart may lose the profit comparison.
Your Supplier Doesn’t Know Your Real Margin
A supplier can quote a wholesale price.
They may also provide product dimensions, packaging information, production lead time and shipping estimates.
But the supplier usually does not have the complete picture of a retailer’s operating costs.
Those costs may include marketplace fees, local warehousing, last-mile delivery, customer service, damaged goods, promotions and markdowns.
A competitive factory quotation can therefore produce very different results for different buyers.
For example, Teruier’s MY3105 Vintage Gold Arch Wall Mirror has published dimensions of 89 × 4 × 60.5 cm and a net weight of 6.3 kg.
These specifications help the buyer evaluate the product’s physical characteristics and potential handling requirements.
However, they cannot establish its retail contribution margin without the buyer’s actual commercial data.
The same applies to Teruier’s TDS27-08 Pastel Three-Piece Nesting Trunk Set, which includes three different decorative storage sizes.
Its dimensions, packaging arrangement and ordering configuration may influence logistics and retail economics, but actual landed costs and customer demand must be confirmed.
Good sourcing starts with accurate product information.
Good profitability decisions require the buyer to combine that information with the economics of their own sales channel.
Stop Measuring Only Margin Percentage
Another misleading habit is focusing entirely on gross margin percentage.
A product may have a high margin percentage but generate relatively little profit because it sells slowly.
Another product may have a lower percentage but produce substantial gross profit through higher sales volume.
Retailers should therefore distinguish between:
Gross margin: The difference between net sales and the cost of goods sold.
Contribution: What remains after the additional costs included in the buyer’s chosen contribution model.
Inventory productivity: How effectively the investment held in inventory generates gross profit.
A useful inventory measure is Gross Margin Return on Inventory Investment, or GMROI.
The basic formula is:
GMROI = Gross Profit ÷ Average Inventory at Cost
A GMROI of 2 means the business generated $2 of gross profit during the measured period for every $1 of average inventory investment at cost.
The measure should be calculated using consistent time periods and inventory valuation methods.
Importantly, GMROI and contribution profit are not interchangeable. A buyer needs both operational and financial context.
For additional guidance on the calculation, see Shopify’s GMROI guide.
A Bestseller Can Consume More Than Money
Some products also occupy disproportionate operational resources.
A large mirror may require more protective packaging, handling space and specialized storage arrangements than a compact tabletop accessory.
A decorative storage trunk may occupy substantial warehouse volume depending on its carton dimensions and whether the final products can be packed together.
An upholstered stool may require different protection against surface damage, deformation or fabric contamination.
These are product-specific considerations, not claims that any category always performs worse than another.
Buyers should examine three questions:
- How much contribution does the product generate?
- How much inventory capital does it require?
- How much space, labour and operational attention does it consume?
The Teruier product specification approach connects dimensions, materials, packing and sourcing information with more realistic commercial evaluation.
A product that looks efficient on a sales dashboard may be less attractive once its complete operating requirements are understood.
But Killing the Bestseller Could Be an Even Bigger Mistake
There is a serious counterargument.
Some bestsellers have strategic value beyond their immediate contribution.
A popular mirror might attract customers into a retail store.
A distinctive vase may introduce shoppers to a wider collection.
A competitively priced tabletop accessory may support purchases of other products.
A low-contribution SKU is not automatically a bad SKU.
The right question is whether it creates measurable value elsewhere.
Does it drive profitable additional purchases?
Does it bring in new customers at an acceptable acquisition cost?
Does it help the retailer sell complementary products?
Would removing it reduce the profitability of the wider assortment?
These effects should be measured using real customer and sales data, rather than assumed from a product’s popularity.
A buyer should not remove a bestseller simply because its unit contribution is lower.
But neither should they reorder it blindly.
Four Possible Decisions Before the Next Purchase Order
A useful retail buying review can classify products into four decisions.
| Decision | When It May Make Sense |
|---|---|
| Grow | Strong contribution, healthy inventory productivity and reliable demand |
| Improve | Strong demand but costs or damage losses need attention |
| Reposition | The product serves a useful role but pricing, channel or merchandising needs adjustment |
| Discontinue | Weak contribution, limited strategic value and no credible improvement path |
For many popular home décor products, improvement should be considered before elimination.
A supplier might be able to review product dimensions, construction, packaging configuration or order quantities.
For example, modifying the protective packaging of a mirror may be worth evaluating if damage costs are reducing contribution.
For a bulky storage product, packaging dimensions and shipment configuration may deserve closer attention.
These changes must be evaluated for safety, product integrity and manufacturing feasibility.
A lower shipping cost is not an improvement if the product becomes more vulnerable to damage.
Teruier’s Mirror Packaging for Shipping explores why packaging must be considered as part of the product’s commercial specification.
What Buyers Should Ask Their Suppliers
A supplier cannot solve a retailer’s entire profit problem.
But the supplier can provide the information needed for better purchasing decisions.
For each important SKU, buyers should request:
- Confirmed product dimensions and weight.
- Final packaging dimensions and gross weight.
- Approved material and finish specifications.
- MOQ and order-quantity pricing.
- Production and replenishment lead times.
- Product-specific packaging and quality information.
- Available development or configuration options.
The buyer can then combine these details with internal sales, logistics, return and inventory data.
Teruier’s Retail Assortment Planning guide discusses how different product roles contribute to a coordinated home décor collection.
This profitability review adds another layer: not only whether the products belong together, but whether each product earns its place commercially.
What This Means for Home Décor Sourcing With Teruier
Teruier works with international buyers on decorative mirrors, tabletop accessories, decorative storage and upholstered accent furniture through product development and manufacturing coordination in Fuzhou–Minhou, China.
A buyer evaluating an existing bestseller may not need a completely new design.
They may need a more efficient version of the current product, a different packaging arrangement, improved specifications or a clearer purchasing configuration.
For example, the starting point could be an existing mirror model whose dimensions and finish are already defined.
The next discussion might examine packaging, sample requirements, material alternatives and production feasibility.
For a decorative storage range, the buyer may need to compare individual products with coordinated sets, while confirming actual packing arrangements and order quantities.
These are potential development discussions—not claims that Teruier has already improved a particular customer’s profit performance.
The objective is to help buyers identify which product changes are commercially worth exploring.
FAQ
Can a bestselling home décor product actually be unprofitable?
Yes. High unit sales do not guarantee positive contribution after relevant product, fulfilment, selling, return and damage costs are considered.
Is gross margin enough to decide which SKU to reorder?
No. Gross margin is important, but inventory investment, direct operating costs, demand and the product’s wider commercial role can also influence the decision.
What is GMROI in retail buying?
GMROI measures gross profit generated during a period relative to the average cost of inventory held during that period. It helps buyers assess inventory productivity.
Should retailers stop buying low-margin bestsellers?
Not automatically. Buyers should investigate whether the product can be improved and whether it supports profitable sales elsewhere in the assortment.
Your Bestseller Should Earn Its Next Purchase Order
The purpose of retail sourcing is not simply to buy products that sell.
It is to build a business in which product demand, purchasing economics and operational performance work together.
A bestselling mirror may deserve more inventory.
Or it may need a new packaging specification, a different sales channel or a more realistic commercial review.
The answer should come from evidence, not from the excitement of a sales ranking.
Teruier welcomes international retailers, importers and home décor brands to discuss product specifications, sample development, packaging and wholesale sourcing.
Contact Teruier to review your next home furnishings product programme.
The next bestseller worth celebrating is the one that earns its place on the shelf—and on the profit report.